

Investments
Life stage (default)
The fund applies a life stage model which automatically takes members through different investment portfolios i.e. aggressive to more conservative portfolios as they near retirement age. The life stages are as follows:
- Members younger than age 55 - Aggressive Growth portfolio
- Members age 55 and older, but younger than age 62 -Capital Growth portfolio
- Members age 62 and older - Stable Growth portfolio
The fund has implemented a phasing-in approach for default switches. Read more

The first 25% switch to the new recommended portfolio will commence at the end of a member’s birthday month. As a result, it will take 12 months for a total portfolio switch to be completed. After the 12 month phase-in period, all future member contributions will automatically accrue to the new default life stage portfolio. See an illustration of a default switch from the Aggressive Growth portfolio to the Capital Growth portfolio below.
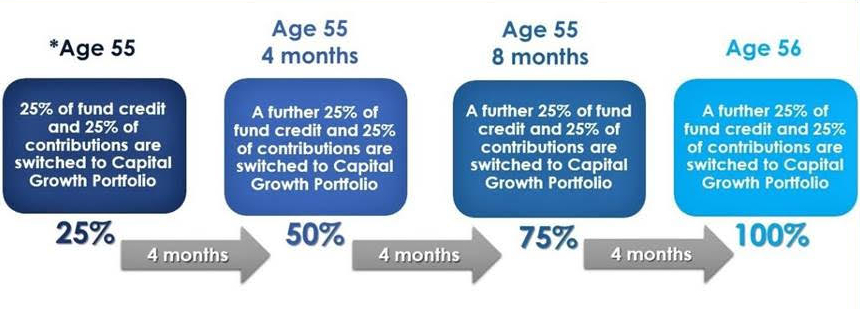
*The first 25% switch to the new recommended portfolio will commence at thee end of a member's birthday month.
Member investment choice
The fund also allows flexibility in providing our members with the option to elect any of the individual investment portfolio options available.
Investment switch form
Aggressive Growth Portfolio
Investment objective: To maximise capital growth over a long-term investment horizon. Members should acknowledge that this strategy could deliver volatile and negative returns over the short-term. This strategy is suitable for members with more than 10 years to retirement.
Capital Growth Portfolio
Investment objective: :To target capital growth over a medium to long-term investment horizon. Members should acknowledge that this strategy could deliver volatile and negative returns over the short-term. This strategy is suitable for members with 5 to 10 years to retirement.
Stable Growth Portfolio
Investment objective: To target stable returns over a medium-term investment horizon with low volatility and a low probability of negative returns. This strategy is suitable for members with 1 to 5 years to retirement.
Capital Protector Portfolio
Investment objective: To provide capital security with very low volatility and an extremely low probability of negative returns. This strategy is suitable for members with less than 1 year to retirement where capital protection is absolutely necessary
Shari’ah portfolio
This portfolio is suitable for Muslim investors requiring a Sharia-compliant investment portfolio. The portfolio will be invested in a variety of domestic and international asset classes. The underlying investments will comply with Shari'ah requirements as prescribed by the Auditing Organisation for Islamic Financial Institutions. The portfolio targets capital growth over the long-term while limiting short term market fluctuations.
Latest investment returns
Economic Commentary: October 2026
October’s data releases showed resilient global economic activity alongside renewed energy-driven inflation pressures, while the ballooning cost and uncertain prospective returns of AI investment weighed on market sentiment.
The advance GDP estimate for the US released late in the month showed third-quarter growth accelerating to an annualised 3.4%, from 2.2% in the second quarter. Growth was supported by healthy consumer spending, government spending, and strong capital investment, particularly driven by artificial intelligence capacity building. September CPI inflation increased to 3.7% year-on-year from 3.4% in August, with a rise in petrol prices accounting for more than half of the 0.6% monthly increase. Core CPI rose to 2.6% year-on-year, while the Fed’s preferred measure, core PCE inflation rose 3.1% year-on-year. Nominal consumer spending increased 0.5% month-on-month, but real spending was broadly unchanged and real disposable income fell 0.3%. The labour market meanwhile remains robust although job growth in recent months has been muted as companies grapple with high inflation and high borrowing costs and consider ways in which artificial intelligence may replace human labour. But while hiring has been slow, lay-offs have also been muted so far. Having raised rates in September for the first time in three years, policymakers at the Federal Reserve voted 10-2 to keep rates steady, opting to assess the incoming economic data and the effects of tightening financial conditions. The Fed acknowledged that economic activity was strong and inflation remained elevated and kept the door open for future rate increases. Futures markets were pricing in a 75% chance of a rate hike in December.
Global equity performance reflected a rotation away from technology rather than uniformly weak participation. The S&P 500 declined 0.9% in October as a 15% decline in communication services stocks and a 7% decline in technology stocks offset gains from the other nine sectors, contrasting with September’s narrow technology-led resilience. Concerns about AI infrastructure spending, cash generation and the timing of investment returns intensified late in the month putting pressure on the NASDAQ and technology- heavy emerging markets. The Nasdaq Composite ended the month down 5.3% while the “old economy” Dow Jones Industrial Average gained 1.8%. The MSCI World Index declined 0.8% while the MSCI EM Index fell 8% as oil supply concerns remained a headwind for energy-importing economies and the unwind of the AI trade led to large losses in China (down 8%) and South Korea (down 15%). Global bonds gained 1.4% as yields in the US dropped while global property stocks added 2.4%.
In South Africa, inflation edged up to 4.5% year-on-year in September from 4.4% in August as transport costs continued rising on the back of higher oil prices and a weaker currency. The SARB projected inflation to remain elevated until the second quarter of 2027 but believes that its current policy approach will bring inflation down to its 3% goal once the initial shocks triggered by the ongoing conflict in the Middle East fade. Economic activity remained subdued with August manufacturing production, released in October, declining 4.3% year-on-year, and retail sales (also August data) rising just 3.3% year-on-year. October’s Medium Term Budget Policy Statement projected growth of 1.2% for 2026, reaffirmed fiscal consolidation and proposed a legislative fiscal anchor to legally restrain public spending and debt. National Treasury projected infrastructure spending to grow at over 5% p.a., noting a R217bn project pipeline, while additional allocations were announced for law enforcement (SAPS and SANDF) and support for victims of gender-based violence.
The local equity market remained under pressure in October, but sector performance diverged. The All Share Index ended down 0.4% for the month driven by a decline of 9.1% in the Resources index as precious metal prices weakened. The Industrials index gained 3.8% as gains in British American Tobacco and retailers offset losses in Naspers and Richemont. Financials added 3.7% thanks to strength in insurers and banks. The rand ended the month slightly weaker at R16.73 to the dollar. The 10-year government bond yield ended the month at 8.73%, a slight decline from September’s 9%, as Moody’s revised the nation’s credit outlook to positive. As a result, the All Bond Index gained 2.1% for the month and listed property stocks added 2%.

Investments FAQs
 Cookie Notice
 Cookie settings